Run this audit once a year. Commissions are the fee brokers advertise, which is why they are $0 almost everywhere: in our dataset of 50 US brokerages, 36 of the 41 brokers with a recorded stock and ETF commission charge exactly $0. A broker dealer fees comparison starts where the advertising stops, with the fees that survive the commission war: mutual fund transaction fees, annual account fees, and inactivity fees. Those are the lines a fee audit calculator app exists to find.
The quiet fees, counted
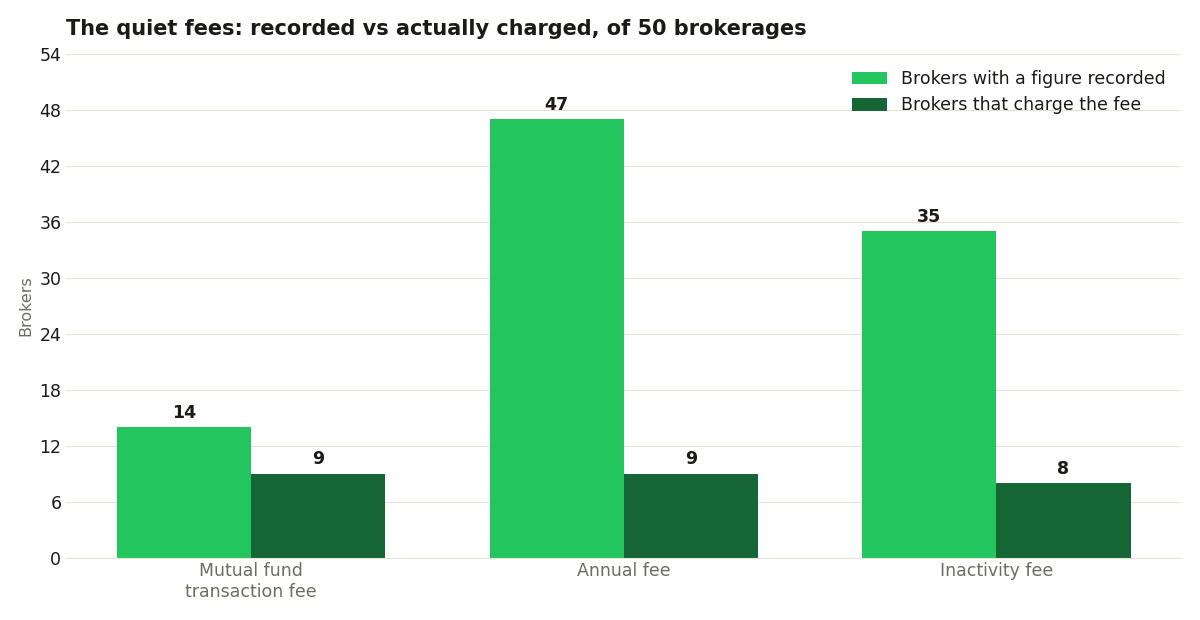
The mutual fund transaction fee is the steepest of the three. Our snapshot records a figure for 14 of the 50 brokers, and 9 of those charge it, with a median of $25 among the chargers. Charles Schwab records the highest at $74.95, Fidelity records $49.95, and Interactive Brokers records the lowest charge at $14.95. This is the fee behind the old warning that a non-house fund can cost up to $75 a buy, and it only appears after you have chosen the fund.
Annual fees are recorded for 47 of the 50, and 9 charge one, from $24 at UNest to $132 at Magnifi, with Greenlight at $131.76. Several of those are subscription-style apps rather than classic brokerages, which is exactly why the audit matters: a subscription reads like a membership, not a brokerage fee, until you annualize it. Inactivity fees are recorded for 35 brokers and charged by 8, from $2 at Avenue Securities to $40 at ChoiceTrade, with names like TradeStation and eToro US at $10. An inactivity fee punishes the most patient investors, the ones who buy and hold for a year without touching the account.
The fees that never print on a statement

Three more costs belong in every audit even though no dataset records them as a line item. Payment for order flow is not a charge, but worse fills cost active traders real basis points. Cash sweep yields are the quiet giant: uninvested cash earning 0.5% while rates sit far higher costs $1,750 a year on $50,000 idle, using the worked example we have always used here. FX spreads take roughly 1% on foreign stock buys, buried inside the exchange rate. None of these appears on a fee schedule, so the audit has to estimate them from your own statements rather than look them up.
What the audit annualizes to
Worked examples make the audit concrete. An investor who buys a non-house mutual fund once a month at Schwab's recorded $74.95 pays $899.40 a year for the habit; at the $25 median among chargers the same habit costs $300, and at a broker that records no such charge it costs nothing. The commission side shows the same shape in miniature: of the 41 brokers with a recorded stock and ETF commission, 36 charge $0, and the five exceptions are specialists, Zacks Trade at $1.00, Tiger Brokers at $0.99, and per-share pricing at CenterPoint, SpeedTrader and Cobra Trading. The lesson generalizes. No single quiet fee ruins an account. The audit exists because three or four of them, annualized, quietly become the largest cost in it.
One honesty note, because an audit is only as good as its gaps. Our dataset does not record outgoing transfer or closeout fees, and it leaves the mutual fund fee blank for most brokers, which means not recorded, not free. A blank in this comparison is a question to ask the broker's official fee schedule, never a zero to bank on.
How to run the audit, and what it finds
Add the recorded fees and the estimated ones together and annualize the total. Most buy-and-hold investors find $50 to $200 in avoidable drag. Active traders often find over $1,000. Fix the biggest leak first, which is usually idle cash, then the per-trade lines. When the audit says your current broker costs more than a rival, price the move before you make it: the SwitchCost Checker builds the cost of leaving from the same recorded fee data, so the comparison runs in both directions. Treat the result as education, not financial advice: the point of a fee audit is not to find a perfect broker, it is to know, once a year, exactly what your broker charges you for the account you actually have.