A good learn-to-invest app teaches five things, in this order:
- Compounding: why starting at 22 beats starting at 32 by multiples.
- Diversification: one index fund beats ten stock tips.
- Costs: a 1% fee versus a 0.03% fee over 30 years.
- Risk: volatility is the price of returns, not a bug.
- Behavior: the app should stop you from panic-selling, not encourage day trading.
The catch is that the teaching only works when it lives inside the account where you actually invest. A standalone course app can explain compounding beautifully and still leave you without a funded account. So the practical question for a beginner is not which course to download. It is which broker builds the teaching features into the account itself. Our dataset of 50 US brokerages records three of those features for every broker: whether the account minimum is zero, whether fractional shares are offered, and whether a paper trading practice account exists.
What the best broker for beginners actually ships
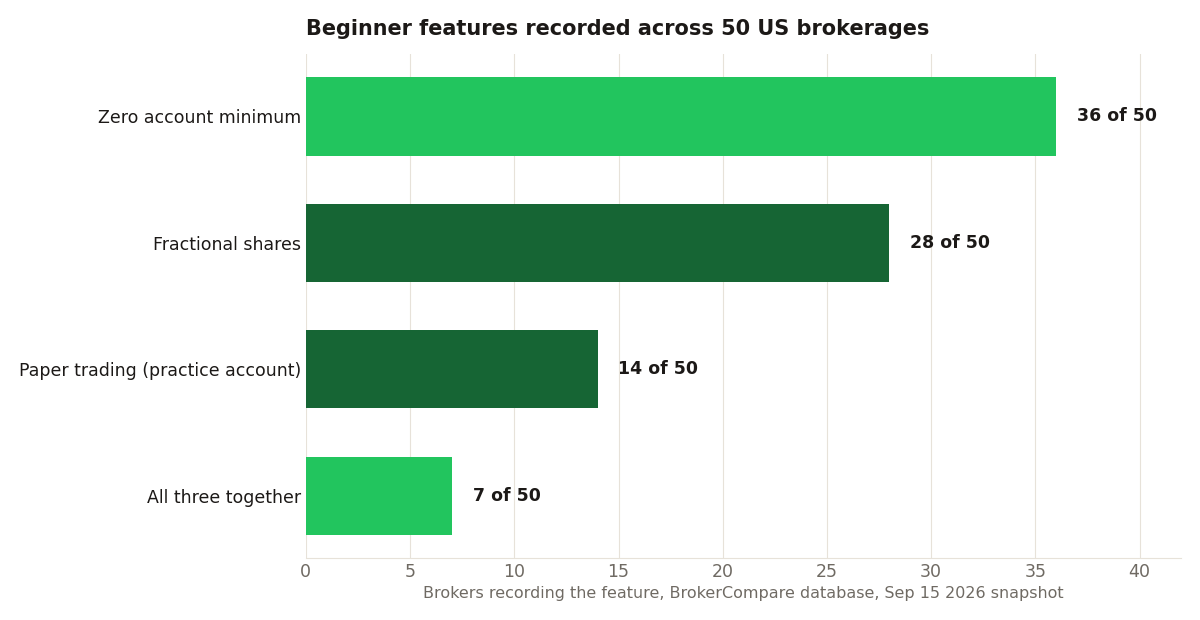
Start with the barrier to entry. 36 of the 50 brokerages record a $0 account minimum, so opening the account costs nothing but time. 28 of 50 record fractional shares, which is the feature that turns a lesson about diversification into a real portfolio: with $50 you can own a slice of a broad index fund instead of waiting months to afford one share of something expensive. The rarest feature is the one that teaches the most. Only 14 of 50 record paper trading, a practice account where you place trades with fake money and watch what your instincts actually do to a balance.
Only 7 of the 50 record all three at once: Charles Schwab, Webull, Interactive Brokers, moomoo, eToro US, Alpaca Securities and Tiger Brokers. That shortlist is a reasonable starting point for a beginner, not because the other 43 are bad, but because these are the accounts where the full learning loop is present: open free, practice without risk, then invest real money in small slices. If your broker lacks paper trading, the honest workaround is a spreadsheet and a month of patience. If it lacks fractional shares, small deposits buy less of the lesson and more of a single stock.

The five lessons, and where each one happens
Compounding is a settings page: it becomes real the day an automatic monthly investment leaves your bank account. Diversification is a search box: it becomes real when the first purchase is a broad fund rather than a tip from a video. Costs are a fee schedule: the dataset behind this site exists because a 1% drag and a 0.03% drag look identical in an app and diverge over 30 years. Risk is a chart you have lived through, ideally first in a practice account. Behavior is the design of the app itself, which brings us to the warnings.
Red flags: apps that gamify trading with confetti, push options to beginners, or hide the education behind a paywall. A broker that profits when you trade often will design lessons that end in a trade. A broker that teaches well designs lessons that end in an automated plan. Zerodha Varsity remains the gold standard for free, structured content, and it is worth reading even if your account sits elsewhere.
The account underneath the lessons
One more beginner decision hides under the features: the account type itself. Our dataset records the account types each broker supports, and the spread is wide. A Roth IRA is recorded at 17 of the 50 brokerages and a traditional IRA at 14, while custodial accounts appear at 10. A beginner who starts in a taxable account at a broker with no IRA on the shelf has not made a mistake exactly, but they have bought a future transfer. The teaching features tell you how you will learn; the account shelf tells you whether the place you learn can also hold the retirement account most beginners should open in year one or two. Check both before the first deposit, because the first deposit is the one that sets the default for every deposit after it.
Check the exit before you commit to the entrance
Beginners rarely ask what it costs to leave a broker, and then they become non-beginners stuck with transfer fees and tax lots. Before you open the account a promotion or a friend recommends, run your current situation through the SwitchCost Checker, which builds the cost of switching from the same recorded fee data used here. Learning and doing should live together: read one module, then automate one investment. That is education, not financial advice: the right broker for a beginner is the one whose teaching features you will still be using in year three.